

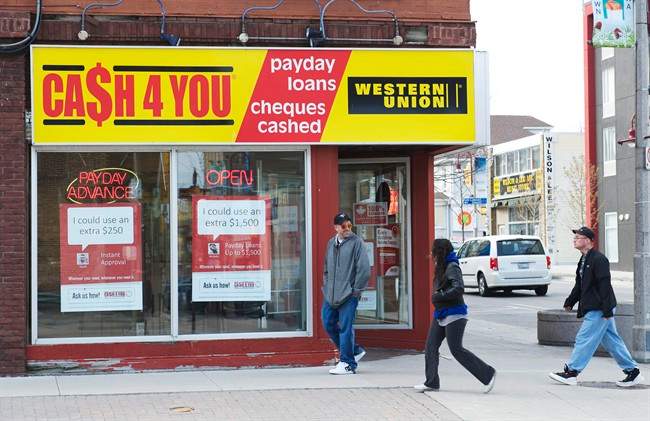
A new report from a public policy think tank is giving Ontario an “F” for capping interest rates at payday loan companies as of Jan 1.

Cardus Work & Economics program director Brian Dijkema notes that capping interest rates offers marginal help to consumers, but doesn’t give them any real alternatives for when they’re desperate for a small, short-term loan.
“If you really want to help, bury the payday loan shops in competition so that consumers have better alternatives to predatory lenders,” said Dijkema. “You can cap interest rates all you want, but that doesn’t help anyone get off the payday loan treadmill.”
The group gives the province a “D” for allowing cities to limit the number of payday loan establishments and where they can be located.
It points to the City of Hamilton’s move to allow only one lender per ward, saying it “leaves borrowers with less choice” and gives existing lenders a local monopoly.
- TC Energy urges co-operation on growing natural gas network to meet ‘generational’ demand
- AI stocks drop as tech companies call to slow down development for safety
- Central Alberta carbon capture hub on track to be largest in Canada
- Enbridge makes US$2.55B acquisition of pipeline, storage systems in U.S. midwest


On the flip side, Cardus gives the province an A++ for allowing credit unions to provide alternatives to payday loan shops.
“This rule change is something we’ve recommended before,” says Dijkema. “Freeing credit unions — which are obligated to benefit their members and their communities — gives them space to try new things and to offer new products.”
Comments
Want to discuss? Please read our Commenting Policy first.